
Book of business · Notes
Why does my new business number look better than my growth?
Short answerA carrier move can create one new policy and one lost policy while the client stays. Count the client relationship first. Then use the line of business and policy identity to tell a rewrite or carrier move from a cross-sell.
John RanieriFounder & Product Lead, Keelridge SoftwareAugust 17, 2026 · 4 min read
What are rewrites and carrier moves, and why do they confuse the count?
Remarketing moves a client you already have to a different carrier, usually at renewal, because of price, appetite, or a carrier exiting a line. A rewrite replaces a policy with one covering the same thing. Both leave the relationship in place.
The agency relationship did not end, but the policy record may change carrier, identifier, and effective date. Without client and policy-line continuity, that replacement can resemble a policy written for a new client.
A report driven only by new and terminated policy rows may therefore count the replacement as both production and churn. One retained relationship creates two misleading policy events unless the report recognizes what persisted.
How badly does this distort the numbers?
It depends entirely on how much remarketing the agency does, which is why the distortion is worst in exactly the conditions where owners most need accurate numbers.
In a hard market, remarketing rises sharply: carriers push rate, appetites narrow, and account managers move business to hold clients. New business appears to surge. Lost business appears to surge alongside it. Neither reflects a change in the client base.
The two errors do not cancel out, because they are usually read separately. New business goes into growth reporting and producer compensation. Lost business goes into retention. Both are wrong in the direction that makes the agency harder to manage.
What does the distortion actually cost?
Three decisions get made on the inflated figure, and all three are expensive to get wrong.
- Production assessment. A producer credited with new business that is actually retained book looks more productive than they are, and a colleague prospecting for new clients looks worse by comparison.
- Compensation. If a compensation report treats every new policy record as new production and new business carries a higher split than renewal, a carrier move can be paid as acquisition work even though no new client was acquired.
- Retention and churn. An inflated churn figure sends owners looking for a service problem that does not exist, and can obscure the real losses hiding inside the noise.
How do you tell a rewrite or carrier move from real new business?
Start with the client. If the client is present at both ends of the period, the agency retained the relationship; the ending of one policy must not become client churn.
Then compare the line of business and a stable policy identity. When the same client keeps the same line but its policy identity and carrier change, the event is a carrier move inside the retained book. When a retained client adds a line on a new policy identity, that can be a cross-sell and therefore new business even though it is not a newly acquired client.
Policy number alone cannot make that distinction reliably. A carrier move can create a new number, while a cross-sell also creates a new policy. Client, line, carrier, policy lineage, and the two endpoint dates have to be read together.
What should new business actually mean?
For Keelridge's Book and team views, new business starts with annual premium on new clients' lines and lines added for existing clients, then leaves out returning lines and rewrites. Purchased policies arriving with an acquired book stay outside that figure; a new sale to a purchased client can still count. Internal reassignment alone is not new business.
A rewrite is not new business. When a staying client replaces a policy with one covering the same thing, under a new line code within 45 days or with the same line of business at another carrier, Keelridge keeps the policy at its old premium and counts only the price difference, as a rewrite. A different coverage is a dropped line plus new business. A line returning after a gap is not new. Client arrivals therefore need classification before they can be read as real growth, and new business can also come from added lines without a new client.
The underlying components should remain available so an owner can tell which kind of growth occurred rather than reading one unexplained total.
What the fix looks like
Movement classified by client, not by policy.
 Owner viewOpen this page in the live demo →
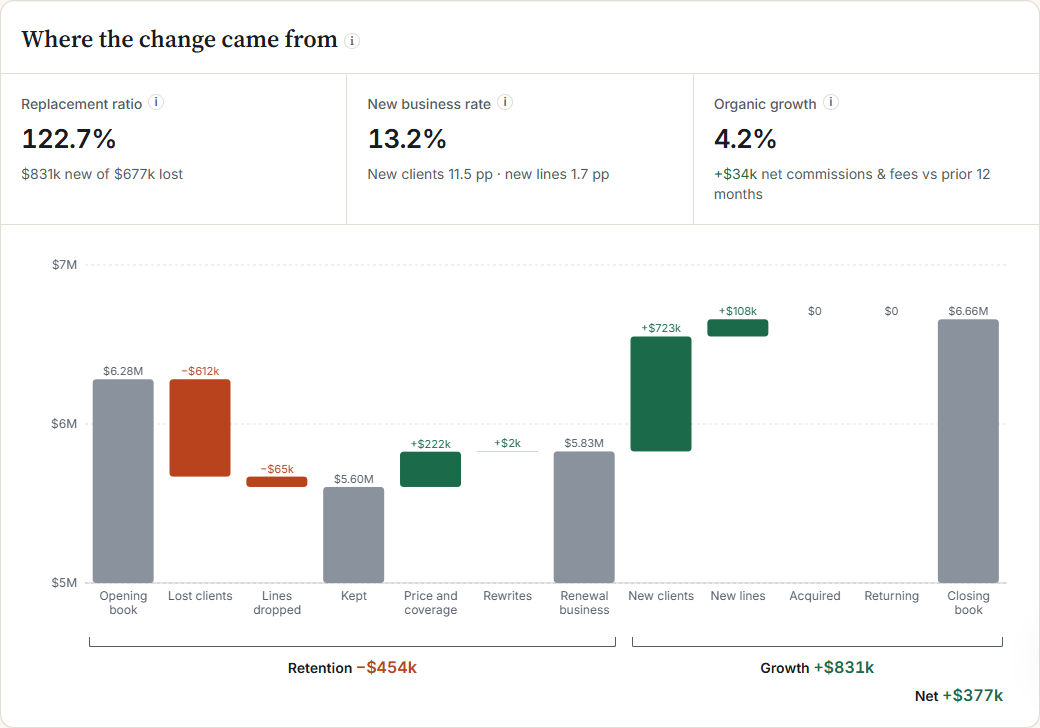
Fictional Keelridge Demo Agency, twelve months to September 30, 2026. A rewritten or moved policy stays in the retained book; only its price change shows, under Rewrites. New clients and New lines are counted apart. Here rewrites moved the book by $2k, while new clients added $723k and new lines $108k. Counted the old way, every rewritten policy would have been one loss and one sale.
What to do with this in your own review
Take last quarter's new-policy list and first separate clients already present in the opening book. For those retained clients, compare line and policy identity: a new line on a new identity may be cross-sell, while the same line moved to a new carrier is a carrier move. Keep both components visible rather than calling every new row either acquisition or churn.
Sources used for the industry context
- Trusted Choice: Retention and Remarketing in a Challenging MarketIndependent-agency reporting on increased remarketing pressure, carrier appetite, and the work required to move retained clients between carriers.
- Agency Performance Partners: How to Measure Customer Retention in an AgencyIndustry guidance describing how rewrites can download as a cancellation plus a new-business policy and can distort retention and producer compensation.