Book of business · Notes
Why does my new business number look better than my growth?
Short answerA carrier move can create one new policy and one lost policy while the customer stays. Count the customer relationship first. Then use the line of business and policy identity to distinguish a remarket from a genuine cross-sell.
John RanieriFounder & Product Lead, Keelridge SoftwareAugust 3, 2026 · 4 min read
What is a remarket, and why does it confuse the count?
A remarket is moving a client you already have to a different carrier, usually at renewal, because of price, appetite, or a carrier exiting a line.
The agency relationship did not end, but the policy record may change carrier, identifier, and effective date. Without customer and policy-line continuity, that replacement can resemble a policy written for a new customer.
A report driven only by new and terminated policy rows may therefore count the replacement as both production and churn. One retained relationship creates two misleading policy events unless the report recognizes what persisted.
How badly does this distort the numbers?
It depends entirely on how much remarketing the agency does, which is why the distortion is worst in exactly the conditions where owners most need accurate numbers.
In a hard market, remarketing rises sharply — carriers push rate, appetites narrow, and account managers move business to hold clients. New business appears to surge. Lost business appears to surge alongside it. Neither reflects a change in the customer base.
The two errors do not cancel out, because they are usually read separately. New business goes into growth reporting and producer compensation. Lost business goes into retention. Both are wrong in the direction that makes the agency harder to manage.
What does the distortion actually cost?
Three decisions get made on the inflated figure, and all three are expensive to get wrong.
- Production assessment. A producer credited with new business that is actually retained book looks more productive than they are, and a colleague doing genuine prospecting looks worse by comparison.
- Compensation. If a compensation report treats every new policy record as new production and new business carries a higher split than renewal, a remarket can be paid as acquisition work even though no new customer was acquired.
- Retention and churn. An inflated churn figure sends owners looking for a service problem that does not exist, and can obscure the real losses hiding inside the noise.
How do you tell a remarket from real new business?
Start with the client. If the customer is present at both ends of the period, the agency retained the relationship; the ending of one policy must not become customer churn.
Then compare the line of business and a stable policy identity. When the same customer keeps the same line but its policy identity and carrier change, the event is a remarket inside the retained Book. When a retained customer adds a line on a genuinely new policy identity, that can be a cross-sell and therefore genuine new business even though it is not a newly acquired customer.
Policy number alone cannot make that distinction reliably. A remarket can create a new number, while a cross-sell also creates a new policy. Client, line, carrier, policy lineage, and the two endpoint dates have to be read together.
What should new business actually mean?
For Keelridge's Book and team views, genuine new business starts with annual premium on new clients' lines and lines added for existing clients, then removes returning lines and the replacement credit on rewrites. Purchased policies arriving with an acquired Book stay outside that figure; a genuinely new sale to a purchased client can still count. Internal reassignment alone is not new business.
When a line replaces one the same client dropped within 45 days, Keelridge credits the replacement up to the value it replaced; only eligible excess counts as new business. A line returning after a gap is not new. Customer arrivals therefore need classification before they can be read as genuine growth, and new business can also come from added lines without a new customer.
The underlying components should remain available so an owner can tell which kind of growth occurred rather than reading one unexplained total.
What the fix looks like
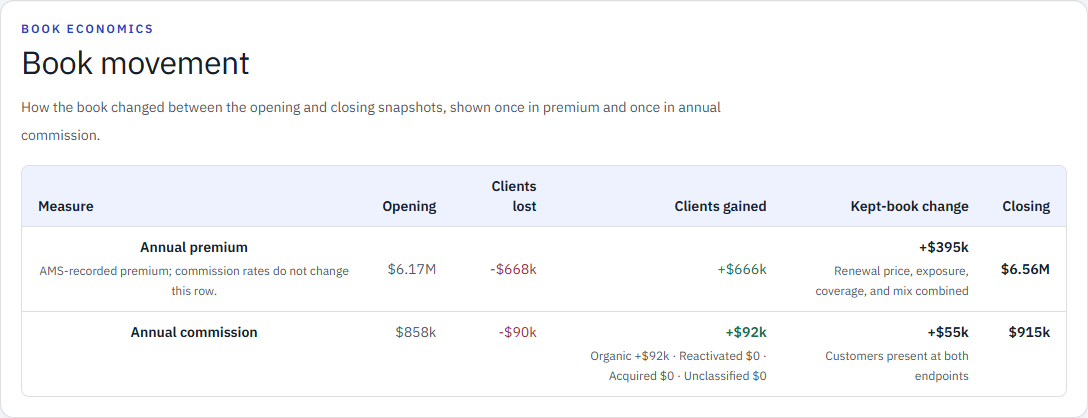
Movement classified by customer, not by policy.
 Owner viewOpen this page in the live demo →
Fictional Keelridge Demo Agency. Customer presence across two snapshots separates retained, lost, and gained relationships. Inside the retained group, line, carrier, and policy-identity evidence distinguish cross-sell, remarketing, dropped lines, and other renewal or mid-term change.
What to do with this in your own review
Take last quarter's new-policy list and first separate customers already present in the opening Book. For those retained customers, compare line and policy identity: a new line on a genuinely new identity may be cross-sell, while the same line moved to a new carrier is a remarket. Keep both components visible rather than calling every new row either acquisition or churn.
Sources used for the industry context
- Trusted Choice — Retention and Remarketing in a Challenging MarketIndependent-agency reporting on increased remarketing pressure, carrier appetite, and the work required to move retained clients between carriers.
- Agency Performance Partners — How to Measure Customer Retention in an AgencyIndustry guidance describing how rewrites can download as a cancellation plus a new-business policy and can distort retention and producer compensation.