Book of business · Notes
What is the difference between premium retention and client retention?
Short answerClient retention counts how many opening customers stayed. Premium retention measures how much of that same group's opening premium stayed with them. The gap shows whether the customers who left were larger or smaller than average. Renewal price changes belong in a separate measure.
John RanieriFounder & Product Lead, Keelridge SoftwareAugust 10, 2026 · 4 min read
What does each number actually measure?
Start with one group: the customers active at the opening date. Client retention divides the number of those customers still active at the ending date by the opening customer count. A household paying $900 and a manufacturer paying $90,000 each count once.
Premium retention follows the same opening customers but weights them by their opening annual premium. It divides the opening premium attached to customers who stayed by the opening premium of the full cohort. That keeps renewal rate, exposure, and coverage changes from changing the retention result after the cohort was set.
Commission retention is the third primary lens in Keelridge. It follows the same opening customer cohort but weights each relationship by its opening annual recurring-commission earning power rather than by premium or by customer count.
Why do client and premium retention disagree?
Because they weight the same departures differently. If the customers who left were larger than the average opening account, premium retention will be lower than client retention. If the customers who left were smaller, premium retention will be higher.
Suppose an agency keeps 92 of 100 customers. Client retention is 92% no matter which eight left. But if those eight represented 14% of opening premium, premium retention is 86%. If they represented only 4%, premium retention is 96%.
Neither result is a substitute for the other. Together they show whether relationship losses were concentrated in economically larger or smaller accounts.
Where do renewal rate increases appear?
Not in Keelridge's premium-retention percentage. Retention freezes each opening customer's weight at the opening date so the measure answers one question: how much of the starting Book stayed attached to customers who remained.
The closing premium on retained customers may still rise or fall because of carrier rate, exposure, coverage, audits, limits, and account mix. Keelridge shows that separately as change on retained customers. Keeping it outside retention prevents a rising renewal price from disguising the economic size of customer departures.
Keelridge also shows a renewal rate beside retention: this year's annual commission on renewed lines, over last year's book commission. Its bridge starts with commission kept, subtracts lines dropped by customers who stayed, then adds price and coverage changes on continuing lines and credited replacements. The difference between renewal rate and commission kept therefore does not isolate price and coverage changes alone.
Other organizations may use a closing-premium convention and still call the result premium retention. That is why a percentage needs its cohort, weighting date, and formula attached before it can be compared with another report.
So which number should an owner use?
Use both, and keep commission retention beside them when the owner needs the recurring-revenue lens.
Use client retention to see the share of relationships retained. Use premium retention to see how much opening premium was concentrated in the customers who remained. Losing ten small accounts and losing one large one are different Book events even when the client count is the same.
Use commission retention to weight the opening cohort by annual recurring-commission earning power. Premium and commission can diverge when commission rates or billing characteristics differ across the accounts that stayed and left.
Then read change on retained customers separately. That is where the Book records the combined effect of rate, exposure, coverage, audits, and mix on relationships that remained.
Why do two systems report different retention for the same period?
Almost always because they are not measuring the same population, and the definition is buried.
- The denominator. Is it everything in force at the start of the period, or only what actually reached its renewal date within it? These produce materially different answers.
- Cancellations versus non-renewals. A mid-term cancellation may be excluded from a renewal-based measure entirely, even though the customer is gone.
- Rewrites and remarkets. Moving a client to a different carrier can register as one policy lost and one gained, which understates retention while the customer never went anywhere.
- Line-level versus account-level. Counting each coverage line separately makes a multi-policy household look like several retention events instead of one relationship.
What should a monthly review show?
Both measures, from a named snapshot period, with the definition attached — and ideally the movement behind them: what was retained, what was lost, what was gained, and what merely transferred between producers.
A single blended retention percentage with no definition is the least useful number in agency reporting. It cannot be challenged, it cannot be compared to a benchmark honestly, and it hides the one trend an owner most needs to see.
What this looks like in practice
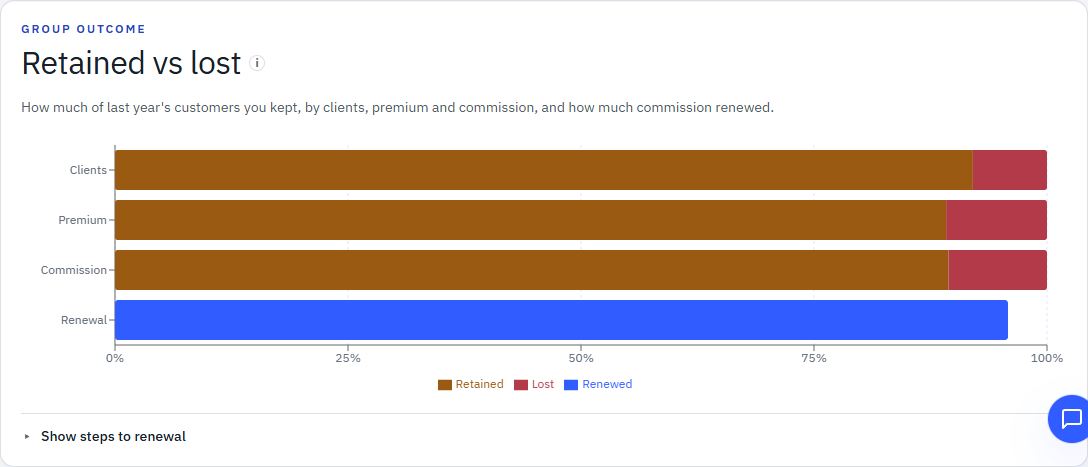
One cohort, weighted three ways.
 Owner viewOpen this page in the live demo →
A synthetic example. Every bar starts from the same prior-year cohort; only the opening weight changes. Premium retention is lowest here because the customers who left carried more opening premium than average. Commission falls between the other two because the lost accounts' commission weight differed from their premium weight.
Why one number a year is not enough
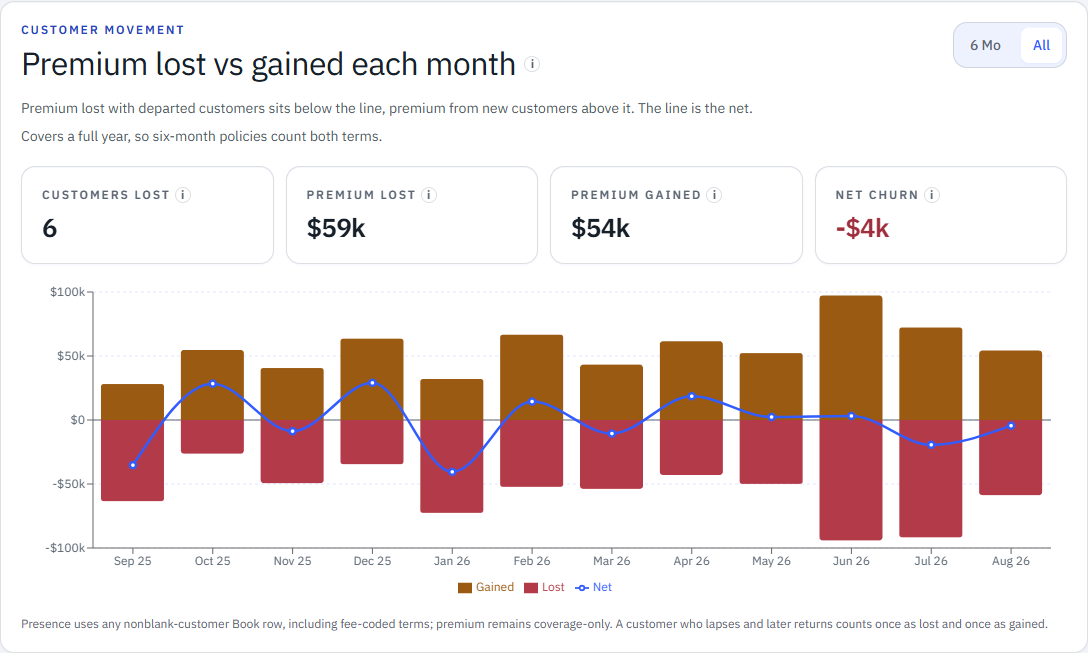
Premium lost and gained, month by month.
 Owner viewOpen this page in the live demo →
A synthetic example covering the same twelve months as the retention percentages above. Monthly movement shows whether departures and arrivals clustered or continued steadily. Those patterns help an owner decide where to investigate; they do not establish a service problem or explain why customers left.
What to do with this in your own review
Find your current retention number and ask four questions: what opening cohort is being followed, whether customers or dollars are being weighted, which date supplies the dollar weight, and how rewrites and transfers are treated. If the report cannot answer all four, do not compare its percentage with another system's yet.
Sources used for the industry context
- IndependentAgent.com — Activity Reporting: Measuring the Heartbeat of the AgencyIndustry discussion of customer, premium, and commission retention as distinct measurements rather than one interchangeable rate.
- Goosehead Insurance — 2025 Form 10-KA public-company example that defines client retention explicitly and reports a premium-basis measure separately, illustrating why the basis must be stated before comparing rates.